A Chinese podcast · Same story, 4 levels
State Farm 拒赔屋顶,一年少赔十四亿美元:最先反对的,是它自己的代理人
State Farm Denied Roof Claims to Save $1.4 Billion
About this story
Unsealed Oklahoma court documents allege State Farm systematically cut roof-damage payouts, keeping $1.4 billion in a single year — and its own agents wrote letters trying to stop it. Chinese listening practice at four levels. HSK 5-6 Chinese listening practice.
This is an HSK 5-6 Chinese listening episode that runs about 9 minutes. The full Mandarin script is shown with tap-for-pinyin and a line-by-line English translation, so you can listen and read at once — comprehensible input in the sense of Stephen Krashen's i+1 theory. It teaches 12 key vocabulary words such as 信任、目标、数据 and walks through 3 grammar patterns, each explained in English with examples. The same news story is retold at 4 difficulty levels — use the level selector above to find the version that is challenging but still understandable for you.
Read at your level
原文Read the complete story in Chinese. Reveal pinyin and English only when you need them.
English transcript reference
Every month you hand money to a company, and you have done it for over a decade without missing once.
What is it you actually bought?
A promise: on your unluckiest day, I will be standing on your side.
This August, a court in Oklahoma unsealed thirty-one internal documents.
The company at the center of them is State Farm, the largest home insurer in America.
The documents show that starting in 2020, the company systematically pushed down roof claims.
Within a single year, one point four billion dollars less was paid out.
Today we are going to take this apart and see how it actually happened.
Some background first.
This stretch of the American middle has a nickname: hail alley.
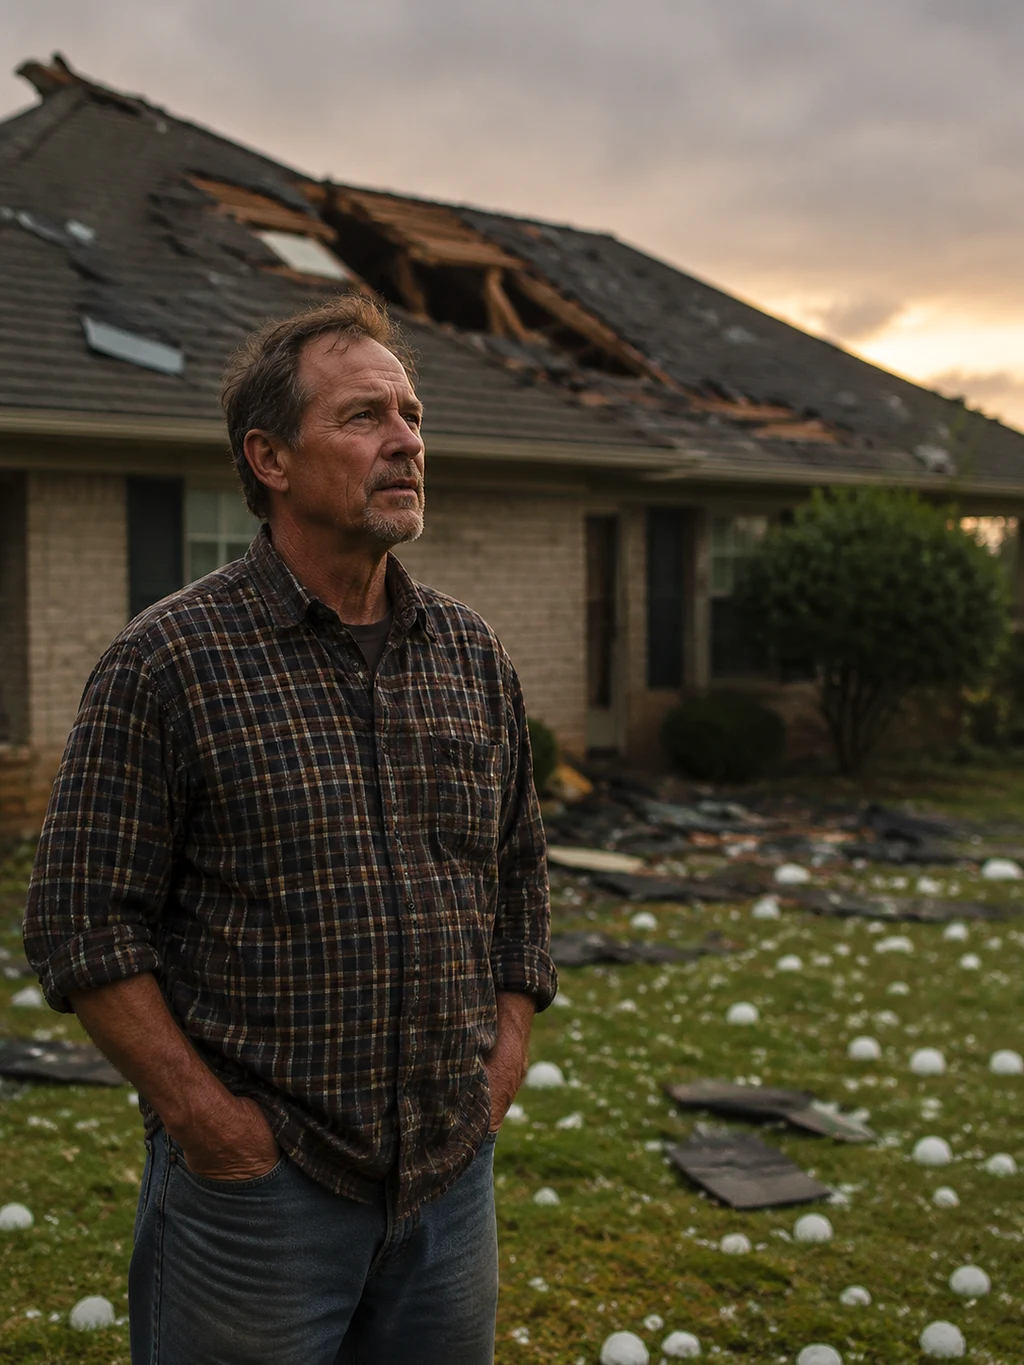
Every spring and summer, hail the size of eggs comes down and wipes out roof after roof.
Replacing a roof on an ordinary house runs about ten to thirty thousand dollars.
The vast majority of American families cannot produce that cash, so home insurance is close to standard.
If you have a mortgage, the bank will require you to carry it.
This is a market you have no way to opt out of.
You have to pay, and you have no choice but to trust.
Trust is exactly what State Farm has run on.
Founded in 1922, more than a century in business, its slogans are ones several generations of Americans can recite.
Inside the company a long-standing line hung over everything: we pay what we owe, not a penny more, not a penny less.
That line began as a standard of conduct written for employees, and only later became advertising.
Once you understand the weight of that sentence, you can understand why what followed stings so much.
The turning point came in June 2020.
State Farm launched an internal program in Dallas County, Texas.
By the end of that year, the program had been extended to all fifty states.
What it targeted was very specific: full roof replacement.
A senior executive with twenty-seven years at the company called it, in internal communications, "our biggest bucket of opportunity."
She also described the program as her own passion project.
In the insurance business, the word "opportunity" showing up in the claims process is itself worth being wary of.
Because the claims process exists to check facts.
So how exactly was it brought down?
The path in the documents is quite clear.
Step one was setting a reference number.
The company cited a supposed national average: an overall replacement rate of eight to ten percent for hail claims, five percent for wind.
And what was State Farm's own rate at the time?
Eighty-five percent for hail, sixty-five for wind.
So "converging toward the average" became the goal.
Listen closely to where the logic breaks.
Whether a given house needs a repair or a replacement is an engineering question, answered on site.
Convert it into a percentage the whole company has to hit, and claims handling stops checking facts and starts hitting targets.
Step two was adding approvals.
A frontline adjuster used to be able to call it on site; now a full replacement had to be escalated for another layer of management review.
Every extra checkpoint lowers the cost of saying no and raises the cost of saying yes.
Step three was training.
The company built a dedicated training module teaching adjusters how to open this conversation with a customer.
The module was called "the Art of the Conversation."
An elegant name. The content, put plainly, was how to smoothly restate "we're replacing it" as "we'll patch it up."
Step four was dashboards.
The company built data dashboards tracking replacement rates region by region and person by person; whoever's number ran high got asked about it.
Four steps in, the effect was immediate.
Before 2020, each single repair corresponded to roughly five point six replacements.
By 2023, that ratio had fallen to two point one.
In money the picture is even plainer: in one year alone, one point four billion dollars less paid out.
The most interesting part of this is that the first people to raise the alarm were its own.
State Farm runs on a captive agent model, with more than nineteen thousand agents across the country.
These agents live in small towns; their customers are their neighbors, their fellow churchgoers, the parents of their kids' classmates.
When something goes wrong, the customer's first call goes to them.
In the autumn of 2021, several agents wrote to management one after another.
One of them wrote: that old line of ours — we pay what we owe, not a penny more, not a penny less — we cannot live up to it anymore.
He said we are now paying extremely low, and customers have to fight us repeatedly to get what already belongs to them.
Another agent complained that the claims department had become a kind of secret society, where agents could not even get an update on a case.
The people who wrote those letters were all still employed.
What they wanted was to pull the company back to what it had been.
The company received the letters.
The program kept going.
So where does this stand legally?
Oklahoma has accumulated more than a thousand lawsuits against State Farm.
One hundred twenty-five consolidated bad-faith cases settled quickly, not long after plaintiffs' lawyers got hold of that batch of sealed documents.
The settlement itself says something.
The state attorney general stepped in directly and filed suit against State Farm.
A judge ordered the company to produce eight hundred thousand internal documents; the company claimed all of them were trade secrets.
In the end, out of forty-four disputed documents, the judge approved releasing thirty-one, running a hundred fifty-nine pages.
The executive who drove the program at the time will be questioned for a third time.
The chief financial officer who chaired the relevant financial meetings is now the head of the company, and he too has to testify.
The first cases are set for trial this November and December.
And what does State Farm say for itself?
The company responded that all of this falls under normal business operations.
It also stressed that it has paid out more than a billion dollars in severe-weather claims in Oklahoma, and that it is proud of its team's work helping communities recover.
Here I want to be fair: that response is not without merit.
The insurance industry does face a real long-running problem: roof fraud.
Some contractors go door to door pushing homeowners to file claims, talking localized damage up into a total loss, and sometimes damaging the roof themselves.
That kind of thing pushes up premiums for everyone, and an insurer wanting to tighten its review has a defensible starting point.
So the real dispute here lands on the question of what you tighten it with.
If the company's approach had been more site inspection and higher evidentiary standards, that is governance.
The approach the documents show is setting a national percentage first, then sending the front line out to reach it.
The difference between those two is the difference between checking more accurately and paying less.
Looked at more deeply, this exposes a structural weakness in the insurance business itself.
The moment you buy insurance, the transaction is not complete.
You hand over certain cash in exchange for an uncertain future promise.
And the moment that promise comes due is precisely when your bargaining power is weakest — your house is leaking, you are desperate to start work, and the other side has lawyers, actuaries, and decades of litigation experience.
This structural asymmetry has shown up more than once in history.
In 1997, Allstate, with help from a consulting firm, ran a similar playbook on claims in New Mexico.
In 2003, the Supreme Court sharply cut a hundred forty-five million dollar punitive damages award in a famous case against State Farm.
Justice Scalia left behind a heavy line at the time, roughly: maybe we have to send them to jail, whatever it takes to stop them.
The implication being that if a fine sits far below the gain, on the company's books it is simply a cost.
One point four billion less paid out in a year, set against the eventual settlement figures — how that math works out is what this case really has to answer.
Two questions to leave you with.
The first is concrete: have you actually read the insurance policy you hold, or did you also just believe the slogan?
The second is bigger: when a company's profit comes from how much of its promise it failed to keep, can the market correct it on its own?
There is no standard answer to these two questions, but they are worth thinking through slowly.
Listen again
Try it without the transcript and notice what sounds clearer.
What vocabulary does this episode teach?
词汇HSK 4. State Farm 靠的就是这份信任 — the asset the company spent a century building and this programme spent.
HSK 4. 于是「向平均值靠拢」就成了目标 — the moment a claim stops being a fact and becomes a number to hit.
HSK 4. 公司做了数据看板 — the dashboards that tracked replacement rates region by region.
HSK 3. Appears both as 管理审核 (the added review layer) and in State Farm's defence, 正常的经营管理.
HSK 3. 对方有律师、有精算师、有几十年的诉讼经验 — the asymmetry you face at the worst moment.
HSK 3. 普通住宅 — the ordinary house whose roof costs more than the family has in cash.
The concept the whole essay rests on: you hand over certain cash for an uncertain future 承诺.
The industry term. The argument is that 理赔 should be a place for checking facts, not finding opportunities.
The specific target of the programme: 整片屋顶的更换.
专属代理人 (captive agents) — nineteen thousand of them, and the first to raise the alarm.
Used in the fair-hearing section: roof fraud 推高了所有人的保费, which is why insurers want to tighten review.
屋顶欺诈 — the genuine problem that makes State Farm's defence not entirely groundless.
* beyond level超纲词
What grammar patterns appear in this episode?
语法每……就……
Expresses a regular consequence: every time A happens, B follows. Useful for describing mechanisms and incentives.
每多一道关口,说「不」的成本就低一分,说「是」的成本就高一分。
从 A 变成 B
Marks a change of state or nature. The essay uses it to name exactly what went wrong — the activity kept its name but changed what it was.
理赔就从核对事实变成了完成指标。
把它换算成一个全公司要达成的百分比。
恰好是……的时候
Points out that two things coincide, usually with an edge — "precisely at the moment when". It sets up the structural argument in the final section.
而承诺兑现的时刻,恰好是你议价能力最弱的时候。
Proper nouns
专有名词Sources
来源Free account
Keep learning from this story
Create a free account to keep saved words and your preferred level together.
- Keep words with their story context
- Remember your preferred level
- Build your vocabulary over time